Rat-infested property is “suitable for use as a dwelling”
The First-tier Tribunal has found that a property in disrepair, inhabited by rodents, is still suitable for use as a dwelling for tax purposes. This sounds illogical - so what’s the full story?
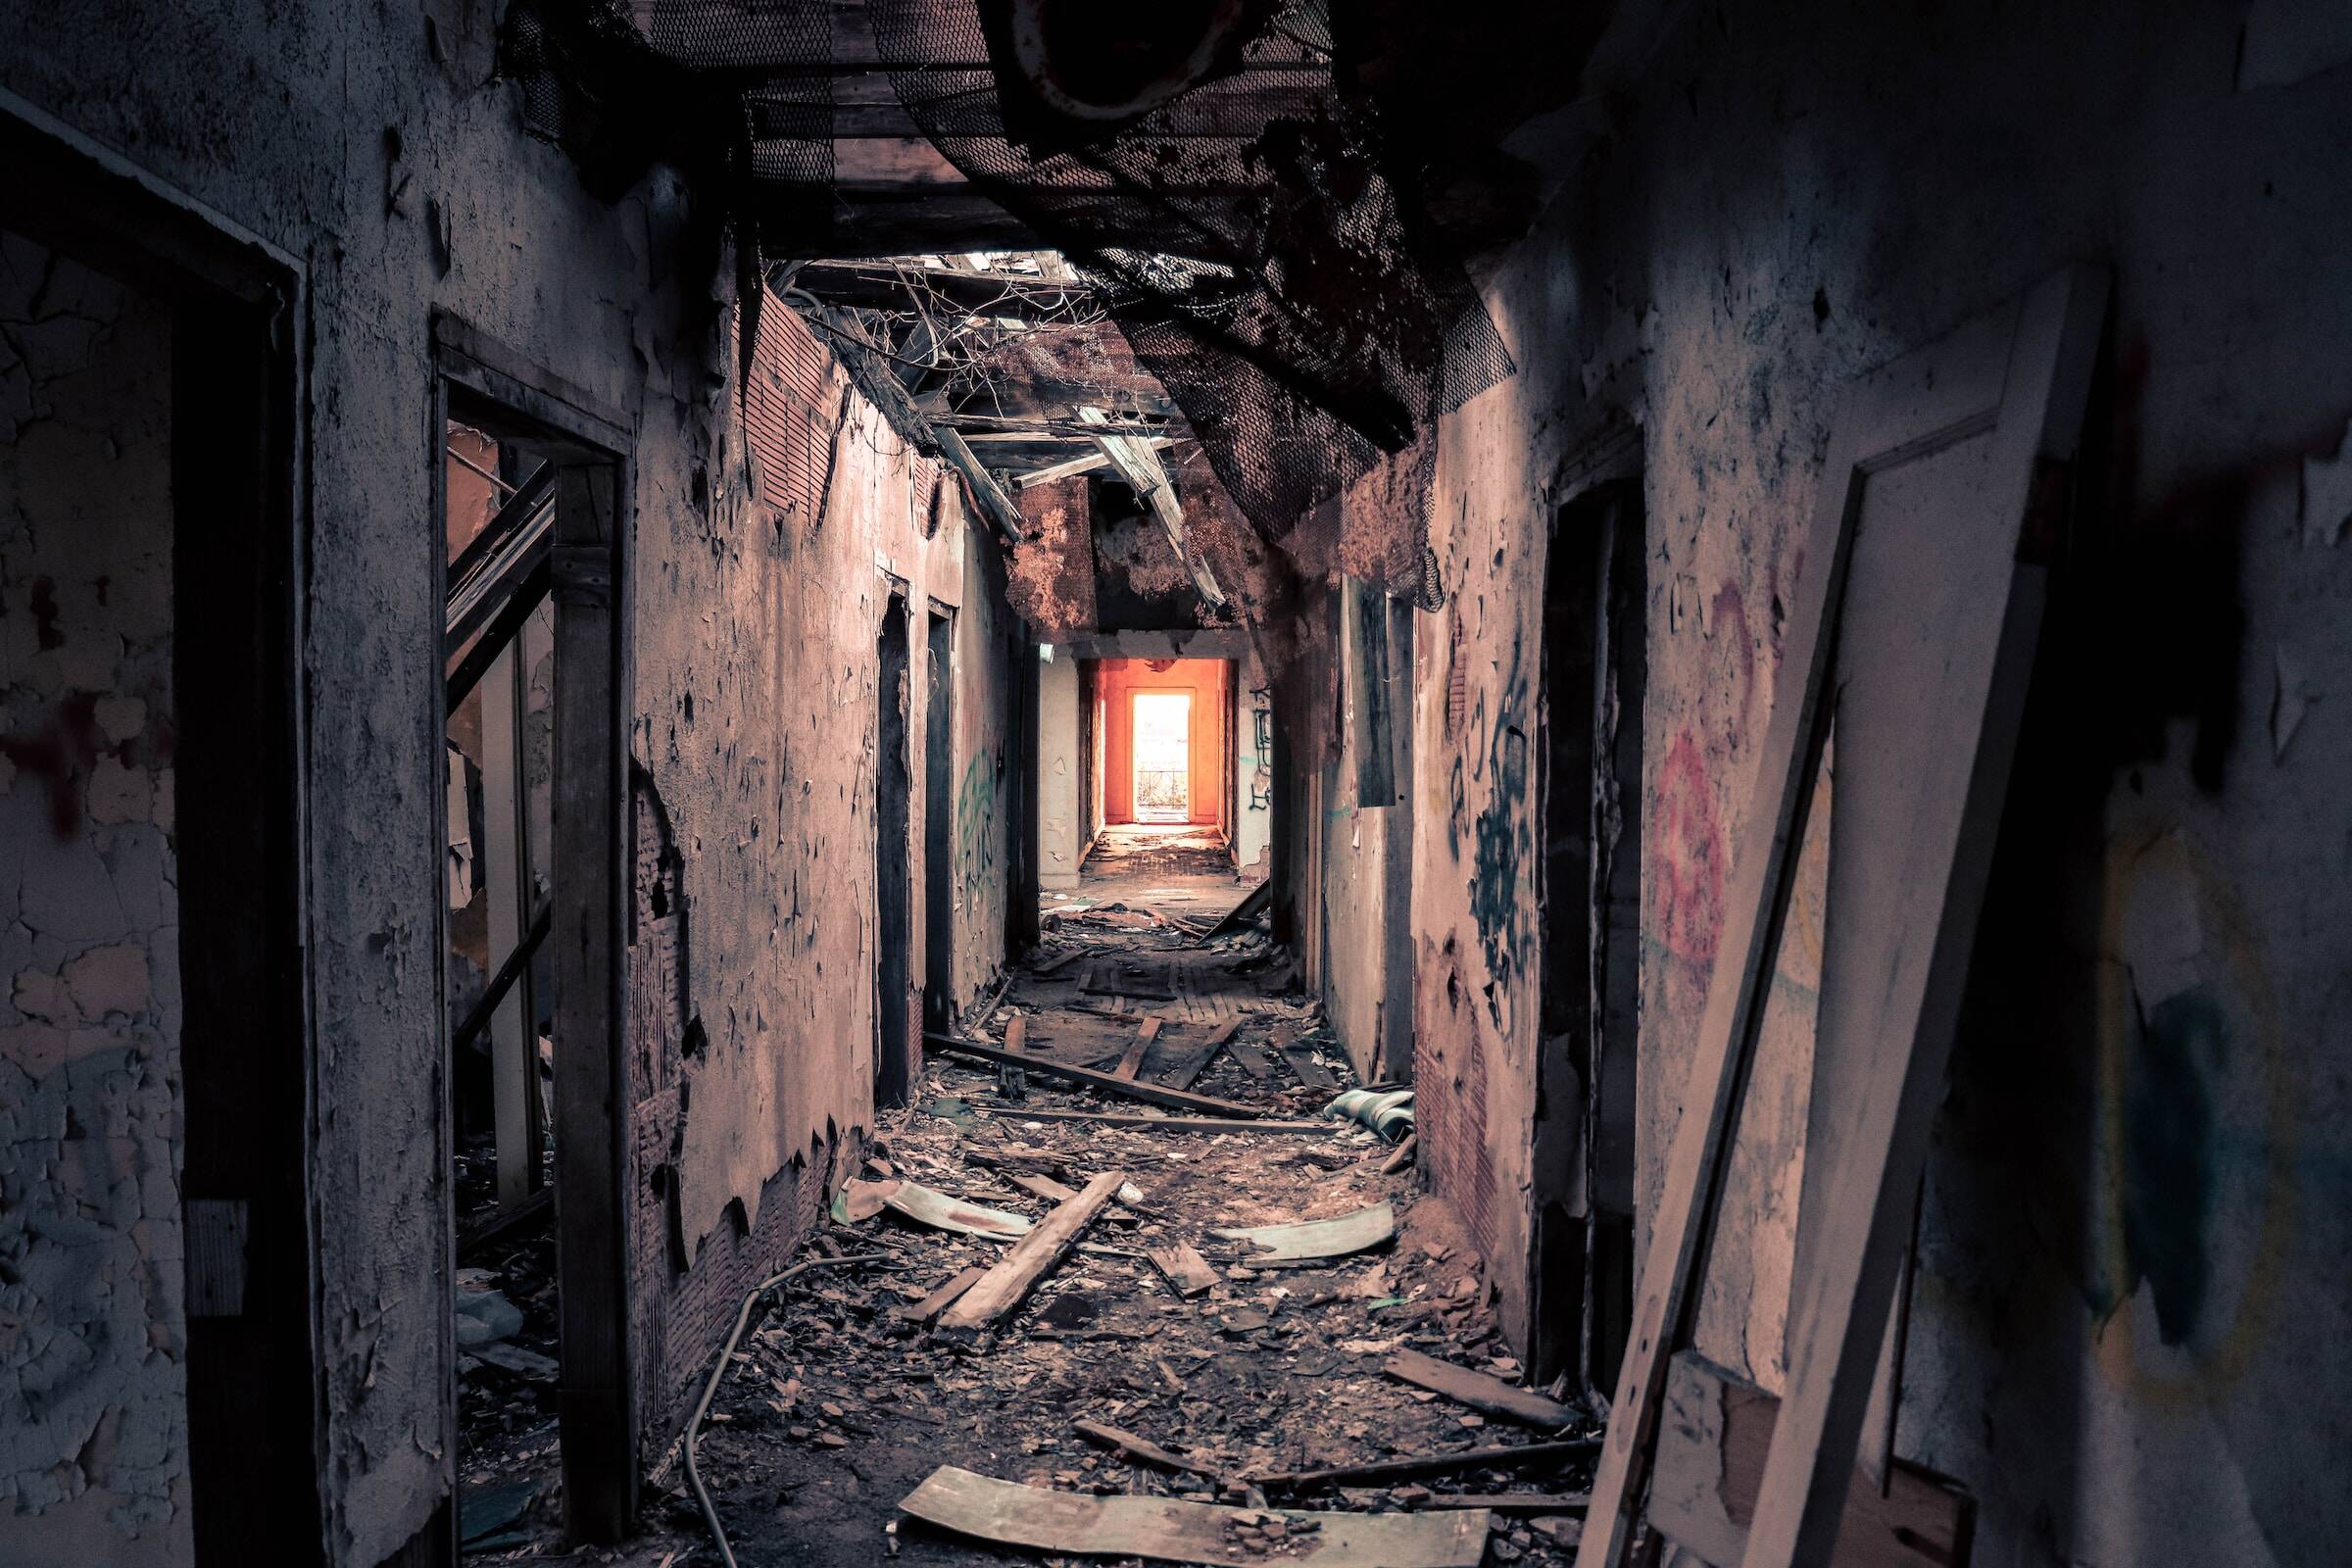
In Mudan & Anor v HMRC the taxpayers (the Ms) purchased a £1.7m property in London that had been empty for five months after the previous tenants were evicted. During that time, the property had been broken into and vandalised, none of the utilities worked and mice and rat droppings covered the kitchen. The boiler had been ripped off the wall, the gas, electricity and water were not functioning safely and rainwater was leaking into the property. It took nine months of renovations before the Ms moved into the property.
Higher rates of stamp duty land tax (SDLT) are chargeable on residential properties, with the pertinent part of the definition being that the property is residential if it is “suitable for use as a dwelling”. Due to the state of the property, the Ms argued that it was not suitable to be occupied and so lower rates of SDLT should apply. HMRC, and ultimately, the tribunal disagreed. The judge confirmed that the bar for a property not to be suitable for use as a dwelling was set very high, and that a building which was recently used as a dwelling, has not in the interim been adapted for another use, and is capable of being so used again will count as a dwelling for SDLT purposes. An additional £100,000 SDLT was due on the purchase, and the appeal was dismissed.
Related Topics
-
Founders' relief: a closer look
The Budget's new Founders' Relief sounds remarkably generous, offering a 10% capital gains tax rate on up to £10 million of gains from selling shares from April 2027. However, a closer look at the proposed qualifying conditions suggests that relatively few business owners will benefit. Why might the relief be so difficult to claim?
-
MONTHLY FOCUS: 2026 BUDGET SPECIAL
Budget 2026 contains a mixture of tax rises, new reliefs and changes to the way businesses and individuals will be taxed from 2027 onwards. Savings and property income will face higher rates, the lifetime limit for Business Asset Disposal Relief will fall, a new founders' relief is planned and several allowances and business incentives are changing. Which measures matter most, and is there anything you should do before they take effect?
-
Autumn Budget 2026 – what are the key tax announcements?
The Chancellor delivered the Autumn Budget on 28 October, announcing a mixture of tax increases, new reliefs and changes to the way tax is administered. Although the headline rates of income tax, National Insurance (NI) and VAT remain unchanged, there are some significant changes affecting business owners, landlords and private individuals. What are the main announcements?
 This website uses both its own and third-party cookies to analyze our services and navigation on our website in order to improve its contents (analytical purposes: measure visits and sources of web traffic). The legal basis is the consent of the user, except in the case of basic cookies, which are essential to navigate this website.